
When an insurer receives hundreds or even thousands of claims every day, the biggest challenge is not simply processing them quickly.
It is deciding which claims need immediate attention, which can follow a standard workflow, and which can safely move through automation.
A cracked windshield should not compete for the same specialist resources as a serious bodily injury claim. A suspicious property loss should not follow the same path as a straightforward, well-documented claim either.
That is where claims triage in high-volume insurance operations becomes essential.
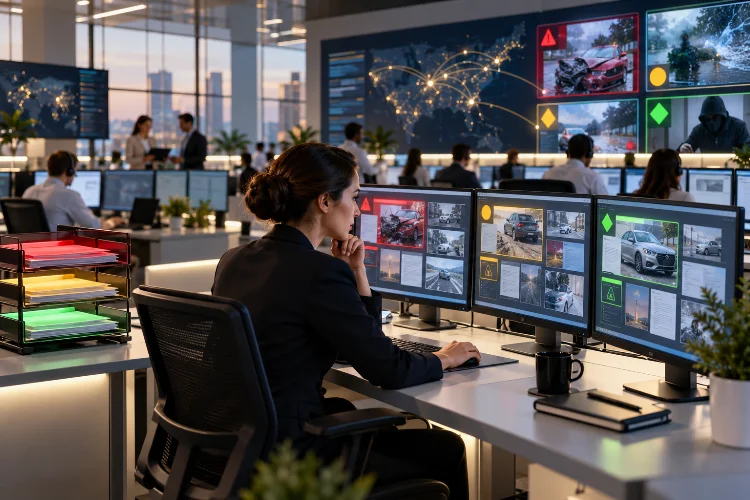
Claims triage evaluates incoming losses and places them into appropriate workflows based on severity, complexity, fraud potential, litigation risk, customer circumstances, and other indicators.
Modern insurers increasingly support this process with predictive analytics, artificial intelligence, and automated decision rules.
The purpose is not simply to process more claims with fewer employees. Good triage directs human expertise toward the cases where it provides the most value while allowing routine claims to move quickly.
For insurers handling massive claim volumes, getting that first routing decision right can influence settlement speed, operating costs, customer satisfaction, and ultimately profitability.
What Claims Triage Actually Does
Claims triage is essentially a prioritization system.
When a new claim arrives, the insurer gathers information about the incident and determines what type of response it needs.
A straightforward auto claim involving minor vehicle damage may qualify for an automated or simplified process. A major collision involving injuries, disputed liability, and several vehicles will probably need an experienced adjuster.
The difference matters because claims resources are limited.
McKinsey has described digital claims models where cases are segmented according to complexity and predicted characteristics, allowing straightforward cases to move toward self-service while more difficult claims are assigned to specialist handlers.
Without this prioritization, adjusters can become overloaded with low-value administrative work while genuinely urgent cases sit in queues.
Triage makes sure the right claim reaches the right workflow as early as possible.
High Claim Volumes Can Quickly Create Bottlenecks
Claims operations rarely experience perfectly consistent demand.
A normal week may suddenly be disrupted by a hurricane, hailstorm, wildfire, flood, cyber incident, or other event generating thousands of claims within days.
Even routine insurance lines can experience seasonal spikes.
When volumes increase, traditional first-in, first-out processing becomes problematic. The oldest claim is not necessarily the most urgent or financially dangerous.
Imagine 5,000 property claims arriving after a severe storm.
Many may involve minor roof damage. Others could involve completely destroyed homes, displaced families, major water intrusion, or safety hazards requiring immediate mitigation.
A good triage system identifies those differences almost immediately.
This prevents high-severity losses from disappearing inside a massive queue of relatively simple cases.
Automation also provides scalability. Routine cases can continue moving through digital workflows even when human adjusters are facing unusually heavy workloads.
First Notice of Loss Is the Critical Starting Point
Effective triage begins with the first notice of loss, commonly called FNOL.
This is when the insurer first learns what happened.
The quality of information collected during FNOL strongly influences every decision that follows. Useful details might include the location, cause of loss, injuries, parties involved, property damage, photographs, police reports, and emergency circumstances.
Modern digital intake tools can structure this information immediately.
Instead of requiring an adjuster to manually read every submission, claims systems can identify important keywords, extract information from documents, analyze images, and compare new claims with historical patterns.
This makes triage faster.
But speed alone is not enough.
Incomplete information can send a claim into the wrong workflow. Insurers therefore need intake systems that gather enough detail without forcing customers through excessively long forms while they may already be dealing with a stressful event.
Good FNOL design creates a foundation for accurate triage rather than simply collecting a claim number.
Severity Scoring Helps Prioritize Expensive Claims
One of the most important triage questions is simple:
How expensive could this claim become?
The answer is not always obvious from the initial reported amount.
A minor injury may develop into an expensive medical claim. Small property damage may uncover major structural problems. A relatively ordinary liability incident might eventually become litigation.
Predictive severity models can help identify these cases earlier.
Insurers can analyze information such as injury characteristics, accident circumstances, policy limits, geographic location, repair estimates, previous claims, and historical outcomes.
Claims with low predicted severity may stay in streamlined workflows.
Cases showing potentially severe outcomes can immediately receive additional attention.
This early escalation matters because experienced adjusters have more opportunities to investigate evidence, coordinate specialists, establish reserves, communicate with involved parties, and prevent avoidable cost escalation.
In high-volume environments, severity scoring keeps expensive claims from becoming invisible among thousands of routine files.
Fraud Screening Is Part of Smart Triage
Not every claim requiring special attention is necessarily large.
A relatively small claim can contain strong fraud indicators.
Fraud detection therefore forms another layer of claims triage.
Modern insurers can evaluate relationships among claimants, previous losses, repair shops, medical providers, addresses, vehicles, timing patterns, and other information.
Claims that appear ordinary can continue toward settlement.
Suspicious cases can be escalated for additional investigation.
This selective approach is much more practical than manually investigating every claim.
Regulatory and industry guidance increasingly recognizes the use of predictive analytics and AI in areas such as claims handling and fraud detection.
The important principle is that automated screening should support appropriate investigation rather than automatically assuming an unusual case is fraudulent.
That balance matters.
Weak fraud screening increases claim leakage. Overly aggressive screening creates unnecessary delays and frustrates legitimate customers.
Good triage aims to achieve both speed and control.
Automation Works Best After Good Triage
Insurers often talk about automating claims, but automation without accurate triage can create new problems.
The safest claims to automate are usually those with predictable characteristics.
Coverage is clear. Documentation is complete. Severity is limited. Fraud indicators are low. Liability is straightforward.
These claims may qualify for straight-through processing, where much of the journey happens with little manual intervention.
Documents can be extracted automatically, policy details verified, damage estimates reviewed, and payments triggered according to predefined rules.
This allows human adjusters to spend more time on complex losses.
Industry technology discussions increasingly emphasize this model: automation handles well-defined, high-volume claims while ambiguous or higher-value cases are routed to people with relevant expertise.
The efficiency gains can be significant because many claims organizations still spend substantial employee time on repetitive administrative activity.
Good triage decides where automation is appropriate.
Litigation Risk Requires Early Attention
Some claims become expensive because legal complexity appears later.
Liability disputes are especially vulnerable.
An injury claim that looks routine during the first few days may become substantially more costly once attorneys become involved, responsibility is disputed, or treatment expands.
Claims systems can therefore consider litigation propensity during triage.
Historical patterns may reveal combinations of circumstances associated with a higher probability of legal escalation.
Claims with these characteristics can be assigned earlier to experienced handlers.
The goal is not to settle every potentially litigated case immediately.
Rather, early recognition gives insurers more options.
Adjusters can secure evidence, document conversations, investigate liability, establish realistic reserves, or explore an appropriate settlement while information is fresh.
Finding the problem on day three is usually better than discovering it six months later.
Catastrophe Claims Make Triage Even More Important
Claims triage becomes particularly valuable during catastrophes.
A major weather event can generate enormous claim volumes within hours.
Insurers need to quickly distinguish customers who have minor damage from those facing unsafe homes, severe structural losses, displacement, or urgent business interruption.
Geographic data can help identify properties within the hardest-hit areas.
Images, satellite information, weather data, and digital damage assessments can further support prioritization.
This allows emergency cases to receive immediate attention while simpler claims continue through remote or automated assessment.
The approach also protects claims employees from becoming overwhelmed.
Rather than manually opening files in random order, adjusters receive cases prioritized according to potential impact.
Scalable digital intake becomes especially useful here because automated systems can continue gathering and classifying information even while claim volumes surge far beyond normal levels.
Claims Triage Improves Customer Experience
Operational efficiency is only half the story.
Customers also benefit when their claim reaches the correct handling path immediately.
Someone submitting a simple claim usually wants a fast digital experience with minimal paperwork. They may become frustrated if forced to repeatedly speak with adjusters about something that could easily be handled online.
Customers facing major losses need something different.
A family whose home has been destroyed may want rapid human contact, clear explanations, and assistance coordinating next steps.
J.D. Power’s 2025 U.S. Claims Digital Experience Study highlights how strongly digital claim experiences can affect customer loyalty. It found that adequate status updates remain particularly important, yet insurers successfully provide them only a minority of the time.
The same research found a striking retention gap: 52% of customers rating their digital claims experience as poor or just acceptable were likely to leave or not renew, compared with only 4% among those rating it excellent or perfect.
Good triage supports that experience by giving different customers the kind of service their situation actually requires.
Human Expertise Still Belongs in the Process
Algorithms can evaluate thousands of claims quickly, but they do not make every case simple.
Unusual circumstances will always exist.
A claim might appear low severity statistically while containing details an experienced adjuster immediately recognizes as concerning.
That is why human overrides remain important.
Claims professionals need the ability to challenge automated classifications, move cases between segments, and escalate unusual losses.
Models also require continous monitoring.
If low-risk claims repeatedly develop into large losses, severity thresholds may need adjustment. If too many ordinary cases are sent for fraud investigation, screening rules may be generating excessive false positives.
The best claims triage system therefore combines technology with experienced judgement.
Automation brings scale and consistency. Humans bring context, empathy, negotiation skills, and the ability to recognize exceptions that do not fit historical patterns.
Better Triage Lowers Operational Costs
High-volume insurance operations can become expensive when resources are poorly allocated.
Senior adjusters cost more than basic automated processing. Specialist investigators are limited. Engineers, medical professionals, attorneys, and other experts should be brought into cases when their expertise creates real value.
Triage helps allocate these resources intelligently.
Routine claims receive lightweight processing.
Intermediate cases receive ordinary adjuster attention.
Severe, suspicious, or complicated claims receive specialized handling.
This reduces unnecessary manual touches and can shorten processing queues.
The result is not simply lower administrative expense. Earlier escalation can also reduce claim leakage, improve reserving, identify fraud faster, and prevent complex losses from deteriorating because nobody noticed them early enough.
For a carrier processing hundreds of thousands of claims, small improvements in routing accuracy can translate into meaningfull financial savings.
Claims triage matters in high-volume insurance operations because not every claim deserves the same workflow, priority, or level of human attention.
Without effective triage, routine cases consume valuable resources while potentially severe claims risk being identified too late.
Modern insurers use FNOL data, severity scoring, fraud analytics, litigation indicators, automation, and human judgement to determine the best path for each case.
The result can be faster settlements, better resource allocation, stronger fraud control, lower operational costs, and a better customer experience.
For insurance leaders, the practical priority is to examine what happens immediately after a claim arrives. If every case enters roughly the same queue, there is likely room for improvement.
Smarter triage does not mean automating everything – it means giving every claim the level of attention it actually needs.
