
Not every insurance claim needs the same level of attention.
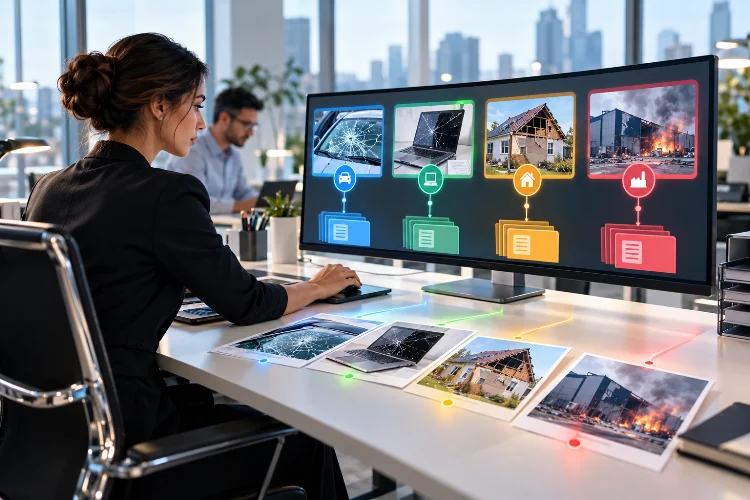
A cracked windshield, a stolen laptop, a serious bodily injury, and a multimillion-dollar commercial fire may all enter the same claims organization, but treating them through identical workflows would be slow, expensive, and inefficient.
That is why claims segmentation has become an important part of modern insurance operations.
Instead of sending every case through the same process, insurers classify claims according to factors such as complexity, severity, fraud risk, litigation potential, customer needs, and expected settlement cost.
Straightforward cases can often move through automated or simplified channels, while complicated claims are routed to experienced adjusters and specialists.
The idea sounds simple, but modern segmentation goes far beyond dividing claims into “small” and “large.”
Insurers increasingly combine first-notice-of-loss information, policy data, historical claims, images, predictive analytics, and artificial intelligence to determine the most appropriate resolution path.
When done well, segmentation can shorten settlement times, reduce operational costs, improve claim accuracy, and give customers a smoother experience when they need their insurer most.
What Claims Segmentation Means in Insurance
Claims segmentation is the process of dividing incoming claims into groups based on their characteristics and expected handling requirements.
A simple claim may have clear coverage, low financial severity, complete documentation, and little indication of fraud or legal complexity. A more difficult case may involve serious injuries, disputed liability, multiple parties, uncertain coverage, or high potential losses.
Those claims should not follow the same journey.
McKinsey describes claims segmentation as a process where AI can classify cases by complexity using both factual information and predicted characteristics. Claims can then be directed toward digital self-service channels or specialist handlers depending on their needs.
The goal is to match resources with complexity.
A skilled senior adjuster should not spend hours manually processing a routine low-value claim that could be resolved automatically. At the same time, a severe liability claim should not remain inside a basic automated queue when early specialist attention could prevent major escalation.
First Notice of Loss Creates the First Segmentation Opportunity
Segmentation often starts with the first notice of loss, commonly known as FNOL.
This is the moment when the insurer first receives information about what happened.
Customers may report the incident through an app, website, telephone call, broker, or other channel. The insurer gathers details such as location, type of damage, injuries, parties involved, estimated severity, and supporting photographs.
Modern systems can analyze that information almost instantly.
For an auto claim, photos might show whether damage appears cosmetic or whether the vehicle is likely to be a total loss. In property insurance, images and location data can help determine whether the claim involves minor damage or a potentially complicated catastrophe loss.
The NAIC notes that AI is increasingly used in claims processing to analyze images, assess damage, estimate repair costs, and support decision-making.
Good FNOL segmentation matters because the first routing decision can influence everything that happens afterward.
Send a complex case to the wrong workflow, and valuable time may be lost before anyone recognizes the problem.
Severity Scoring Separates Routine Claims From Major Losses
One of the most important segmentation factors is expected severity.
Severity refers to how expensive a claim may ultimately become.
A claim initially reported at $2,000 might remain inexpensive. Another claim with similar initial information could eventually cost hundreds of thousands of dollars because of medical complications, litigation, or hidden property damage.
Predictive models help insurers estimate that difference.
They can examine variables such as injury type, vehicle damage, claimant characteristics, location, policy limits, prior claims, repair estimates, and historical outcomes.
Claims with low predicted severity may enter streamlined workflows.
High-severity claims can be transferred immediately to specialists.
This early differentiation matters because severe cases often benefit from faster investigation and more experienced handling.
McKinsey expects advanced analytics to increasingly segment and route claims at FNOL so they reach the appropriate handler and resolution channel quickly.
The earlier an insurer recognizes a high-value case, the more options it has for controlling its development.
Fraud Risk Creates Another Claims Segment
Claims cannot be segmented by financial value alone.
Fraud risk also matters.
A relatively small claim may contain suspicious characteristics that justify additional investigation, while a much larger claim may be completely legitimate and well documented.
Insurers therefore use fraud scoring as part of claims triage.
These systems can analyze inconsistencies, relationships between parties, previous claim behavior, unusual timing, repeated providers, repair patterns, and other indicators.
The NAIC notes that insurers increasingly rely on predictive modeling, link analysis, and artificial intelligence instead of only using traditional fraud red flags.
This does not mean that every unusual claim should be treated as fraudulent.
Good segmentation is about prioritizing investigation.
Low-risk claims can continue through ordinary processing, while cases with stronger fraud indicators may be referred to a special investigation unit.
That helps insurers control claim leakage without making legitimate customers go through unnecessary scrutiny.
Litigation Potential Can Change the Handling Path
Some claims become expensive not because the original damage was unusually severe, but because disputes escalate.
Liability claims are a good example.
An apparently manageable accident can become complicated when attorneys become involved, responsibility is disputed, medical treatment expands, or several parties make conflicting allegations.
Modern claims segmentation can incorporate litigation propensity.
Predictive systems examine patterns associated with claims that historically became litigated and identify cases that deserve earlier specialist attention.
This does not mean insurers should automatically settle every claim that looks likely to involve lawyers.
Instead, early identification gives the claims team more options.
An experienced adjuster might strengthen documentation, contact parties sooner, obtain expert opinions, or explore settlement before positions become entrenched.
Segmentation therefore helps insurers distinguish between claims that can follow normal processing and those where delay could significantly increase costs.
Simple Claims Can Move Through Straight-Through Processing
One of the biggest benefits of claims segmentation is the ability to identify cases that do not require extensive human intervention.
This is known as straight-through processing.
A straightforward claim might have clear coverage, low severity, no suspicious indicators, complete supporting documents, and an easily calculated payment amount.
Instead of waiting for a claims handler to review every step, digital systems can verify information, apply rules, estimate damages, and potentially initiate payment automatically.
Accenture notes that many claims may meet the conditions required for straight-through processing, while AI can help identify these simpler cases and improve efficiency.
The benefit extends beyond operational cost.
Customers also receive faster decisions.
That matters because claims are often stressful. A customer dealing with minor vehicle damage does not want to wait several weeks simply because the insurer’s internal process treats every loss like a complex investigation.
Automation works best when segmentation accurately determines which cases are safe to simplify.
Complex Claims Need the Right Human Expertise
Automation becomes less useful as claims become more complicated.
Serious bodily injury, large commercial property losses, professional liability, cyber incidents, and disputed coverage often require judgement that cannot be reduced to a basic rules engine.
The next challenge is therefore matching those cases with the right people.
Not every adjuster has the same expertise.
A claims professional experienced in construction defects may not be the best person to manage a complex cyber loss. Similarly, catastrophic property claims may require specialists familiar with engineering, business interruption, or large-loss negotiations.
McKinsey has described insurers using “best-match” routing systems to connect individual cases with claims handlers whose experience best fits the problem. In one example, better matching improved handling accuracy by reducing both overpayments and underpayments.
That is smarter segmentation.
It does not merely decide whether a claim requires a person. It determines which person is most likely to resolve it effectively.
Customer Needs Can Also Influence Segmentation
Claims segmentation is often discussed in financial terms, but customer behavior matters too.
Some customers are comfortable managing a claim through an app.
Others may need human support.
Accenture reports that 36% of insurance consumers would ideally like to manage claims through an app or text message.
This means insurers cannot assume one channel works for everyone.
A digitally confident customer with a straightforward claim might prefer self-service from start to finish. Someone experiencing a major house fire or serious injury may value direct contact with an experienced claims professional.
J.D. Power’s 2025 Claims Digital Experience Study found that digital claims experiences have a strong relationship with loyalty.
Among customers rating their experience poor or just acceptable, 52% were likely to leave or not renew, compared with only 4% among those describing it as excellent or perfect.
Segmentation can therefore include service preferences alongside technical claim characteristics.
A smarter claims model asks not only, “What kind of loss is this?” but also, “What kind of support does this customer need?”
Segmentation Helps Reduce Claims Operational Costs
Without segmentation, insurance claims departments can become inefficient very quickly.
Routine cases consume expensive employee time, while difficult cases may sit too long before reaching specialists.
Intelligent routing reduces this mismatch.
Automation can handle repetitive tasks such as document classification, data extraction, basic verification, and status updates. Claims handlers can then concentrate on negotiations, complex coverage questions, severe losses, and exceptions.
McKinsey has argued that digital claims transformation can simultaneously improve customer experience, efficiency, and effectiveness when automation is integrated across the claims journey.
The savings can come from multiple directions.
Fewer manual touches reduce administrative expenses. Better routing can shorten claim cycles. Earlier specialist intervention can prevent high-severity claims from deteriorating.
Even modest improvements become significant across hundreds of thousands of claims.
This is why claims segmentation should be viewed as an operating-model decision, not simply a technology feature.
AI Makes Claims Segmentation More Dynamic
Traditional segmentation often relied on static business rules.
For example, every claim above a certain dollar amount might automatically be sent to a senior adjuster.
Rules like this are easy to understand but can miss important differences.
AI and machine learning can evaluate far more variables simultaneously.
The NAIC notes that insurers now use AI in claims for image analysis, settlement-value estimation, fraud detection, and other decision-support functions.
Machine-learning models can also update predictions as new information arrives.
A claim initially categorized as low risk might be escalated when new medical documents appear. A high-risk case might later become simpler if liability is quickly established and damages are clearly documented.
This makes segmentation dynamic rather than permanent.
That is important because claims evolve.
The information available on the first day rarely tells the entire story.
Human Oversight Still Matters
Claims segmentation can improve efficiency, but insurers cannot treat algorithmic recommendations as unquestionable decisions.
Models can make mistakes.
Poor data, hidden bias, outdated assumptions, or unusual circumstances can lead to incorrect routing.
The NAIC emphasizes that insurers remain responsible for fairness, accuracy, compliance, and appropriate human oversight when AI is used in insurance operations.
This is particularly important when automated systems influence claim outcomes.
A classification model should help claims professionals prioritize work, not create a black box where customers cannot understand why their case was handled differently.
Insurers also need to monitor model performance.
If supposedly “simple” claims repeatedly require reopening or escalation, the segmentation model may need adjustment.
Likewise, if too many legitimate claims are flagged as suspicious, fraud thresholds may be too aggressive.
Smart segmentation therefore requires continous testing and human review.
Claims Segmentation Improves Both Speed and Accuracy
Fast claims are useful only when decisions are correct.
A rushed settlement that overpays damages creates unnecessary losses. An automated denial that misses important information creates complaints and potential regulatory problems.
Claims segmentation helps balance both objectives.
Simple cases receive faster processing because their characteristics support it.
Complex cases receive additional scrutiny because their potential financial or customer impact justifies the effort.
The result is a more proportionate claims operation.
J.D. Power found that customers are especially satisfied when they can manage their claims digitally, yet only 22% receive adequate proactive digital updates consistently.
That suggests there is still substantial room for insurers to improve both routing and communication.
The smartest claims process is not the one with the most automation.
It is the one that applies automation, analytics, and human expertise exactly where each creates the greatest value.
Claims segmentation helps insurers resolve losses faster and more intelligently by matching each case with the right workflow, technology, and level of expertise.
Severity, fraud risk, litigation potential, complexity, customer preferences, and available documentation can all influence how a claim should be handled.
Simple cases can move through automated channels, while unusual or high-risk claims receive specialist attention before costs escalate.
AI makes this process increasingly dynamic, but good governance and human judgement remain essential. Models should support claims professionals rather than replace thoughtful decision-making.
For insurers looking to improve claims performance, the practical next step is to examine where routine cases still receive unnecessary manual attention and where complex claims are identified too late.
Better segmentation at the begining of the journey can improve settlement speed, claim accuracy, operating costs, and customer satisfaction at the same time.
