
Insurance portfolios often look diversified on paper. An insurer might cover thousands of properties, businesses, vehicles, and liability risks across different industries and locations.
At first glance, spreading coverage across many customers should reduce the impact of any single loss. The problem is that those risks may not be as independent as they appear.
A hurricane can damage thousands of insured buildings at the same time. A cloud service failure can interrupt businesses across unrelated industries. One defective component can trigger product liability claims across dozens of manufacturers.
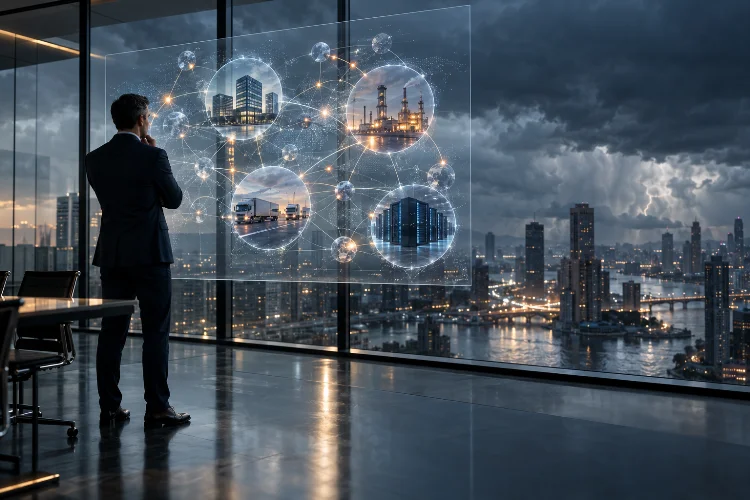
This is where risk correlation in portfolio-level insurance strategy becomes critical. Correlation describes the extent to which different exposures can experience losses at the same time or because of the same underlying event.
When correlations rise, diversification becomes less effective and potential portfolio losses can increase dramatically. Modern insurers therefore need to look beyond individual underwriting quality.
They must understand how risks interact across the entire book, where hidden concentrations exist, and whether pricing, capital, and reinsurance strategies still make sense when multiple losses occur together.
What Risk Correlation Means in Insurance
In simple terms, risk correlation measures how closely different insurance losses can move together.
If two risks are completely independent, a loss affecting one should have little influence on the other. If they are highly correlated, the same event or underlying factor may generate claims from both.
Property insurance provides an obvious example.
Two buildings located thousands of miles apart may have relatively low catastrophe correlation. Two buildings located in the same hurricane-prone coastal zone have much higher potential correlation because one storm could damage both.
Correlation becomes more complicated in modern commercial insurance.
Two companies may operate in different industries and cities but depend on the same cloud provider. A major cloud outage could therefore generate business interruption, cyber, professional liability, and other claims across both companies.
Swiss Re notes that shared electricity grids, telecommunications infrastructure, cloud services, and specialized suppliers can create increasingly correlated losses across different insureds and insurance lines.
That changes how insurers need to think about diversification.
Diversification Works Only When Risks Are Truly Different
Diversification is one of the foundations of insurance.
An insurer can absorb individual losses more easily when those claims occur independently across a large portfolio. Premium collected from many policyholders helps fund losses experienced by a smaller number.
But diversification becomes weaker when exposures share common drivers.
Imagine an insurer covers 1,000 warehouses across ten cities. That might sound geographically diversified.
However, suppose 700 of those warehouses belong to businesses relying on the same logistics network, electricity provider, or technology platform. A major infrastructure failure could suddenly affect hundreds of policies at once.
The portfolio is more concentrated than the geographic map suggests.
This is why insurers increasingly examine relationships between exposures rather than simply counting how many policies or locations they have.
Swiss Re has highlighted that interconnected businesses, outsourcing, data dependence, and complex supply chains can produce accumulation scenarios with unexpected scale.
Effective diversification therefore depends on understanding the underlying loss drivers, not just visible policy categories.
Correlation Turns Individual Risks Into Accumulation Risk
One policy can look perfectly acceptable on its own and still make a portfolio more dangerous.
This happens through accumulation risk.
Accumulation, sometimes called clash risk, occurs when one event produces losses across multiple policies or business lines.
A large industrial explosion might trigger property damage, employee injuries, business interruption, environmental liability, directors and officers claims, and losses at neighboring businesses.
Swiss Re defines accumulation risk as potential loss exposure created when a single event spreads across multiple lines of business within an insurer’s portfolio.
The key challenge is that these connections are not always obvious during individual underwriting.
An underwriter reviewing one factory may conclude that the account is attractively priced. But portfolio analytics could reveal that the insurer already has substantial exposure to nearby suppliers, transportation infrastructure, and businesses depending on that facility.
The new policy might therefore increase aggregate risk far more than its standalone expected loss suggests.
Catastrophe Modeling Makes Correlation More Visible
Natural catastrophes are among the clearest examples of correlated insurance losses.
A major hurricane does not damage one random property. It creates a geographic footprint affecting thousands of buildings simultaneously.
Catastrophe models help insurers understand this portfolio-level relationship.
The NAIC explains that catastrophe models simulate thousands of plausible events and apply them to underlying insurance portfolios. They incorporate hazard, vulnerability, exposure, policy conditions, and financial terms to estimate potential losses.
The important part is aggregation.
Instead of simply estimating expected damage to one property, insurers can see how one simulated storm affects every insured location within its path.
Model outputs can include average annual loss, probable maximum losses, and exceedance probability curves showing the likelihood that portfolio losses will exceed specific levels.
This gives management a much better view of correlated tail risk.
A portfolio might produce excellent average profits but still expose the insurer to an unacceptable loss once every 100 or 200 years.
That possibility can significantly change underwriting and capital decisions.
Correlation Changes How Insurance Is Priced
Traditional pricing often begins with expected loss at the individual account level.
Portfolio-level pricing needs to consider something more: how much additional correlated risk the account adds to the existing book.
Consider two commercial properties with identical expected annual claims.
Property A is located in a region where the insurer has very little existing exposure. Property B sits inside an area where the insurer already has billions of dollars at risk.
From a standalone perspective, both properties may deserve similar premiums.
From a portfolio perspective, Property B can be more expensive to carry because it adds to an existing concentration.
This concept can influence pricing, deductibles, policy limits, and the amount of capacity offered.
Swiss Re’s portfolio analytics tools are specifically designed to analyze large datasets across business lines, geographic areas, and natural-catastrophe zones to uncover accumulation risk and improve underwriting strategy.
Pricing therefore becomes more than estimating the average cost of one policy. It becomes a question of how each policy changes the portfolio’s total risk-adjusted return.
Correlation Affects Where Insurers Deploy Capacity
Insurance companies have finite capital.
That means underwriting teams cannot provide unlimited coverage everywhere, even when individual opportunities look profitable.
Correlation helps determine where capacity should be deployed.
Suppose an insurer has already written substantial hurricane exposure in Florida. Another profitable Florida account may increase concentration more than management wants.
The same insurer might have significant unused capacity in another region where its existing exposure is relatively low.
Portfolio strategy could therefore favor growth in the less-correlated region.
This is increasingly becoming a real-time underwriting consideration.
Swiss Re noted in September 2026 that knowing where exposure is concentrated is not necessarily the same as knowing where an insurer still has capacity to grow.
It argues that portfolio context needs to reach underwriters before new business is bound, rather than appearing weeks later in periodic reviews.
The important question is no longer simply, “Can we insure this?”
It becomes, “Should we insure this given everything else already on the book?”
Reinsurance Becomes More Important as Correlation Rises
Highly correlated portfolios can generate extreme losses from a single event.
Reinsurance allows primary insurers to transfer part of that exposure.
For example, catastrophe excess-of-loss reinsurance can protect an insurer when losses from one major event exceed a specified threshold.
Correlation modeling helps determine how much protection is needed.
If an insurer underestimates the relationship among its exposures, it may purchase insufficient reinsurance. A severe event could then generate losses much larger than anticipated.
Catastrophe model outputs are widely used for reinsurance purchasing as well as pricing, capital planning, and solvency assessment, according to the NAIC.
Correlation also influences how insurers structure reinsurance.
Management might choose different attachment points, limits, geographic protections, or aggregate covers depending on how losses behave across the portfolio.
The objective is not to transfer every risk.
Instead, insurers try to protect the balance sheet from correlated events capable of producing losses far beyond ordinary annual volatility.
Cyber Risk Shows Why Correlation Is Getting Harder to Measure
Cyber insurance demonstrates how modern correlations can differ from traditional catastrophe risk.
With hurricanes, geographic proximity is a major driver.
Cyber losses may spread without respecting geography at all.
Thousands of businesses around the world could use the same cloud platform, software provider, payment system, or cybersecurity technology.
A vulnerability affecting one widely used service could therefore generate claims across many unrelated industries simultaneously.
This creates potential systemic accumulation.
Swiss Re specifically identifies systemic failure and serial aggregation among the scenarios insurers need to examine when evaluating modern accumulation risks.
The challenge is made harder because digital relationships constantly change.
A portfolio that appeared well diversified last year may become increasingly correlated as policyholders migrate toward the same technology vendors or digital infrastructure.
Insurers therefore need continous monitoring rather than static annual portfolio reviews.
Capital Requirements Change With Portfolio Correlation
Correlation also matters because insurers must maintain enough capital to absorb unexpected losses.
Two portfolios with identical expected annual claims can require very different amounts of capital.
Portfolio A might contain thousands of largely independent risks.
Portfolio B might contain similar expected losses but strong correlation, meaning a single extreme event could trigger many claims simultaneously.
Portfolio B generally creates greater tail-risk pressure.
Insurers therefore use stress testing, catastrophe models, and other risk analytics to estimate how the portfolio could perform under severe scenarios.
The NAIC notes that catastrophe-model results are used not only for underwriting and pricing but also for capital and solvency assessment.
This link between correlation and capital creates an important strategic tradeoff.
An opportunity can generate attractive premium while still producing poor returns if it requires disproportionatly large amounts of capital to support the resulting concentration.
Correlation Is Dynamic, Not Permanent
Another important lesson is that correlations can change.
Businesses evolve, supply chains consolidate, technologies become more widely adopted, and infrastructure becomes increasingly connected.
Yesterday’s independent risks can become tomorrow’s correlated exposures.
Recent Swiss Re research emphasizes that infrastructure concentration and interconnectedness are increasing potential insurance loss correlation.
Data centers provide one example: expensive facilities may cluster around electricity, network, water, and specialist supplier infrastructure, allowing one disruption to affect multiple insured parties.
This means portfolio analysis cannot be completed once and forgotten.
Underwriters and portfolio managers need to monitor new business, renewals, changing exposures, vendor dependencies, catastrophe patterns, and emerging systemic threats.
Swiss Re’s 2026 accumulation guidance also stresses that portfolios continually change as policies bind and renew, making timely risk information important for underwriting decisions.
Modern insurance strategy therefore increasingly treats correlation as a moving variable rather than a fixed assumption.
Risk correlation changes portfolio-level insurance strategy because individual risks cannot always be evaluated independently.
Properties, companies, technologies, supply chains, and infrastructure may share hidden connections that cause many policies to experience losses simultaneously.
Understanding these relationships helps insurers identify accumulation risk, improve diversification, refine pricing, allocate capacity, structure reinsurance, and determine how much capital is required.
The challenge is that correlations keep evolving. Digital infrastructure, climate exposure, supply-chain concentration, and emerging technologies can create connections that were previously invisible.
For insurers, the practical priority is to combine individual underwriting with continous portfolio analysis. Before adding another attractive risk, decision-makers should ask how it changes the entire book.
Strong portfolios are not simply collections of good policies – they are collections of risks that remain manageable when the unexpected happens.
